Gleason Insurance Brokers

Developer & Subdivider Insurance · Builders Risk · Subdivision Bonds · General Liability Start a Business Insurance Quote Today

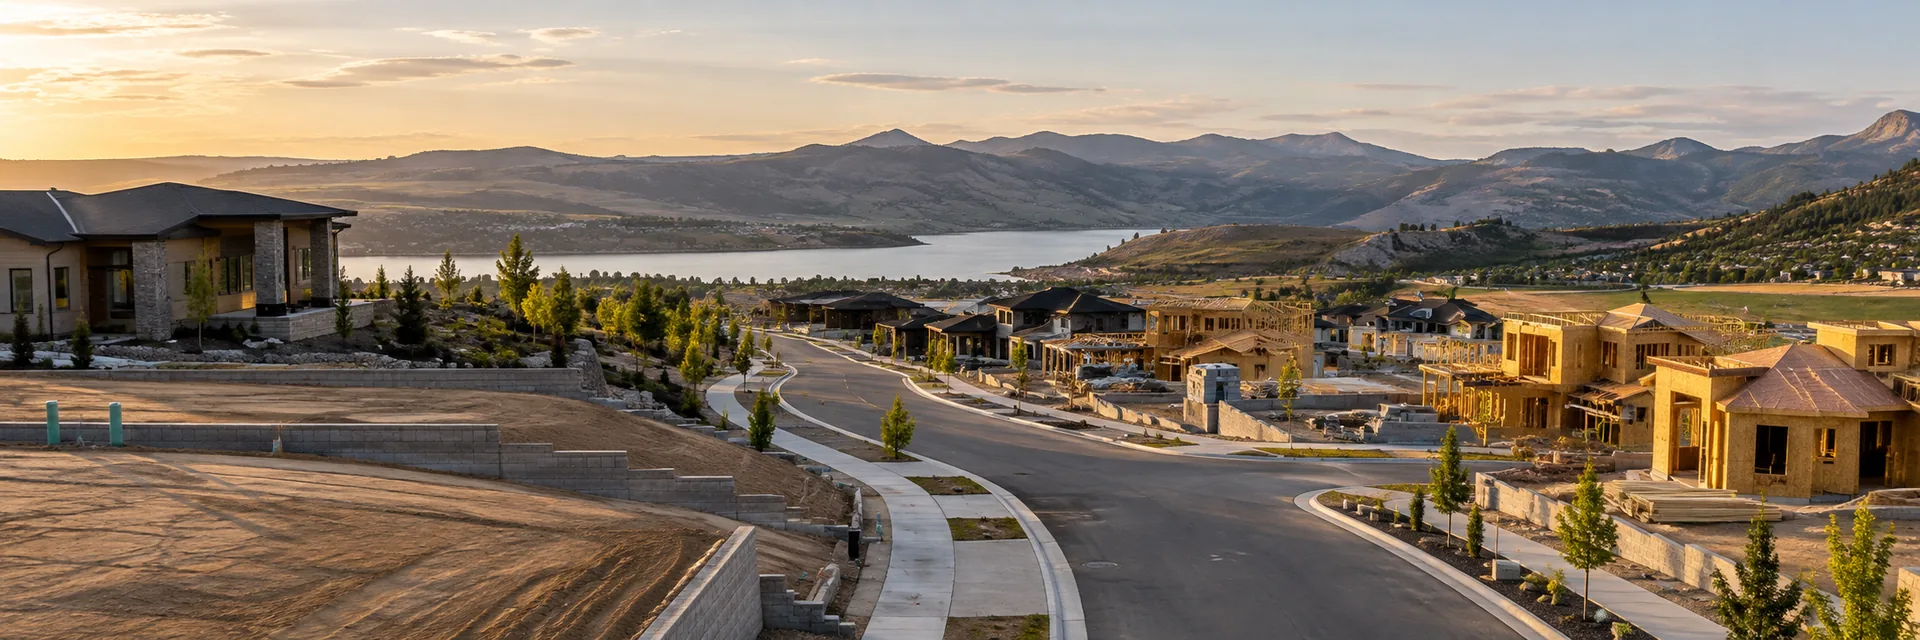
A residential subdivision under construction, framed houses along a new street — developer and subdivider insurance for Utah

Utah commercial insurance

Utah — Developers & Subdividers Insurance

844-97-USAVE

Developers and subdividers active in Utah carry the same lifecycle risk found anywhere — entitlement, construction, and long-tail exposure after homes or units are sold — layered on top of Utah's own regulatory structure for the contractors performing the work.

  • Entitlement to Post-Sale
  • Seismic Design Exposure
  • DOPL-Licensed Contractors

Reviewed by David Gleason, Principal — October 12, 2026

UtahGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability
Builder's RiskProject property during construction

What it is

Builder's Risk may insure covered buildings, materials and certain project property while construction is underway.

Why businesses like yours commonly carry it

Owners, developers and contractors commonly consider it when a structure or major renovation is exposed during construction.

Possible coverage gap

Commercial Property and General Liability are not automatic substitutes for course-of-construction property coverage.

Learn more about Builder's Risk

Commonly Added Based on Operations

Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Developers move deposits, lender draws and investor funds electronically, often across several project entities.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for real estate developers

Exposure-Dependent Coverages

Professional Liability / E&OErrors in professional services or advice

What it is

Professional Liability may address covered claims alleging errors, omissions or failures in professional services.

Why businesses like yours commonly carry it

Businesses providing design, engineering, consulting, specifications or professional advice commonly consider it.

Possible coverage gap

General Liability is generally not intended to replace coverage for economic loss arising from professional errors.

Learn more about Professional Liability / E&O
Contractors Pollution LiabilityPollution conditions and cleanup liability

What it is

Pollution Liability may address covered cleanup costs and third-party injury or property damage arising from pollution conditions.

Why businesses like yours commonly carry it

Businesses working with fuels, chemicals, soil, water, demolition or environmental conditions may have pollution exposures.

Possible coverage gap

Standard General Liability commonly contains pollution exclusions or limitations.

Learn more about Contractors Pollution Liability
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What developers say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Development risk in Utah

Utah's fastest-growing corridor — Salt Lake, Utah and Weber counties along the Wasatch Front — sits directly on or near the Wasatch Fault, one of the most studied and active fault systems in the country, which makes seismic design a genuinely material consideration for larger structures in a way it isn't for most other states in this comparison. This affects structural engineering and, in turn, the professional liability conversation around stamped structural plans on larger Utah developments.

Beyond the Wasatch Front's residential growth, Utah has a distinct mountain and resort-community development sector — ski-resort-adjacent projects around Park City and similar mountain corridors — that carries its own seasonal construction-window and access considerations different from standard valley-floor residential development.

The Wasatch Fault runs directly through the state's primary growth corridor — seismic design is a real consideration for larger structures
Seismic exposure affects the structural engineering and professional liability conversation on larger developments
Mountain/resort-adjacent development (Park City and similar corridors) carries its own seasonal construction-window considerations
Contractors are licensed through the Utah Division of Professional Licensing (DOPL), not CSLB

Coordinating with Utah contractor licensing and bonding

Utah's Division of Professional Licensing (DOPL) licenses contractors by classification, each with its own scope of work (B100, R100 and specialty classes) — the developer's own program sits alongside, not instead of, that contractor-level licensing framework.

Whether or not Utah has a statewide contractor licensing framework, the general contractors, land improvement contractors and subcontractors performing land development work still need their own verified insurance — risk transfer discipline matters the same way it does anywhere.

Coordinate with Utah's actual regulatory structure, not an assumption
Verify GC and subcontractor insurance as part of managing developer exposure
Risk transfer discipline applies regardless of state licensing framework
Confirm current requirements directly with Division of Professional Licensing (DOPL)

Entitlement and project-specific requirements

Local jurisdictions in Utah — cities and counties — set their own conditions for subdivision and development approval, similar in structure to California even where the specific process differs.

Construction lenders generally specify their own builders risk and liability requirements in the loan agreement — review the actual document rather than assuming a standard policy already satisfies it. A real example of this in practice: a lender financing a larger Utah project along the Wasatch Front will typically require the structural engineer's seismic design certification as a closing condition, given the Wasatch Fault's proximity to the state's primary growth corridor.

Municipal development agreement and land use authority runs through the Municipal Land Use, Development, and Management Act, Utah Code §10-20-101 — the current citation following Utah's 2025 recodification, which moved this framework from the old Title 10, Chapter 9a to the new Chapter 20 (a technical renumbering, not a change to the underlying requirements, but worth citing correctly).

Local jurisdictions set their own approval conditions
Lenders specify requirements through the actual loan agreement
Read the actual documents rather than assuming standard coverage fits
Confirm requirements early in the entitlement process

Bonding for subdivision improvements

Subdivision improvement bonding in Utah is sized to the engineer's approved cost estimate and underwritten against developer financial strength, the same mechanics used elsewhere — but winter conditions along the Wasatch Front add a real, seasonal construction-window consideration that affects project scheduling and, in turn, how bonded infrastructure timelines get set. A grading or drainage schedule that doesn't account for a real winter shutdown window can put bonded completion deadlines at risk before the infrastructure work even starts.

Snow load is a real structural design factor on Wasatch Front and mountain-corridor projects — worth confirming the structural engineer's design snow load assumptions are current for the specific elevation and location, since this affects both the stamped plans themselves and the completed structure's long-term risk profile.

Subdivision improvement bonds sized to the engineer's cost estimate, same underwriting mechanics as any state
Winter conditions create a real seasonal construction-window consideration for bonded infrastructure timelines
Snow load is a genuine structural design factor — confirm current design assumptions for the specific elevation
Build winter shutdown windows into the schedule before setting bonded completion deadlines

Working with Gleason Insurance Brokers as a Utah developer

We're licensed to place coverage in Utah alongside our other four states, with the same construction and transportation focus extended to developer and subdivider risk.

Describe your project's scope, phasing and any jurisdiction- or lender-specific requirements — call 844-978-7283 or request a quote to begin the review.

Licensed in Utah and four other states
Same coordinated program approach as our California developer clients
Built around your actual project scope and requirements
Begin with a quote request, or call 844-978-7283

Developer and subdivider insurance by Utah metro

Local pages for the Utah markets where development and subdivision work is most active.

Frequently asked questions

9 questions — start typing to filter

How is developer insurance in Utah different from standard contractor insurance?

It needs to account for the full project lifecycle — entitlement, construction and long after completion — the same as in any state we serve.

Do Utah developers need subdivision improvement bonds?

Typically yes — local jurisdictions require bonds guaranteeing infrastructure completion, sized to the engineer's approved cost estimate for the specific project.

What should I verify about my general contractor's insurance on a Utah development project?

Confirm their completed operations coverage specifically — it's directly connected to your own long-term construction defect exposure as the developer.

Does a Utah construction lender set its own insurance requirements?

Yes — read the actual loan agreement, which typically specifies builders risk, general liability, and sometimes additional coverage as a funding condition.

How long after a Utah development is complete can a defect claim arise?

It can be years, and along the Wasatch Front it helps to separate two things that look similar. A defect claim traces back to the work itself; seismic damage along the Wasatch Fault corridor is a peril question handled by a different policy and often excluded or sub-limited. Mountain and resort-community projects add seasonal access and snow-load factors to the same timeline. Completed-operations coverage with a realistic window is the part to set at inception rather than after the final closing.

Does Gleason Insurance Brokers coordinate bonding and insurance together for Utah developers?

Yes — we coordinate general liability and builders risk as one program and handle the bonding through the same agency, which keeps it in one place without pretending a surety bond is a coverage line.

Does Gleason Insurance Brokers place developer coverage in Utah alongside other states?

Yes — we're licensed in Utah alongside California and our other three licensed states.

Does the Wasatch Fault affect insurance or engineering requirements for Utah developments?

It can — the Wasatch Fault runs directly through Utah's primary growth corridor (Salt Lake, Utah and Weber counties), making seismic design a real consideration for larger structures. This affects the structural engineering itself and, in turn, the professional liability conversation around the engineer's stamped plans on larger developments.

How does winter weather affect subdivision bonding timelines in Utah?

Winter conditions along the Wasatch Front create a real seasonal construction-window that affects grading and drainage infrastructure scheduling — a schedule that doesn't account for a winter shutdown can put bonded completion deadlines at risk. Build this into project planning before setting bonded timelines, not after a delay forces the conversation.

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 12, 2026