Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

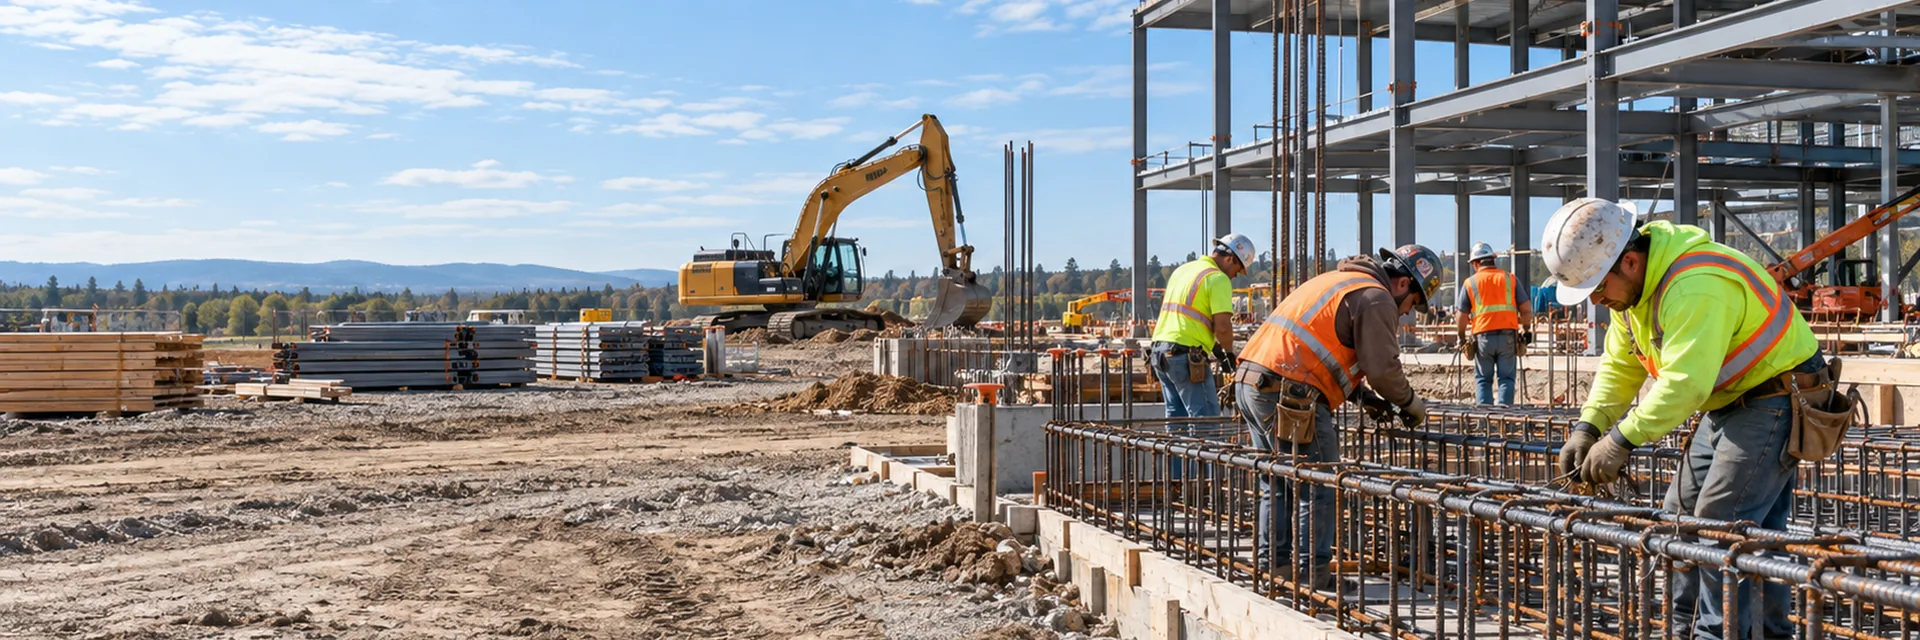
A construction crew working together on an active job site — workers compensation insurance for Nevada contractors

Nevada commercial insurance

Nevada — Workers Compensation Insurance

844-97-USAVE

Nevada calls it industrial insurance, not workers compensation — same underlying concept, state-specific process, and it's required unless a signed exemption affidavit is on file. Working with an independent agency licensed across Nevada instead of a single-carrier agent means faster comparisons and more affordable options for your construction projects.

  • Exemption Affidavit
  • Industrial Insurance
  • Audits

Reviewed by David Gleason, Principal — October 12, 2026

Next Level Experience. Insurance Done Right.

NevadaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability

Commonly Added Based on Operations

Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Modern businesses commonly rely on email, banking, accounting systems, websites, cloud services and electronic records.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about small business cyber insurance in California

Exposure-Dependent Coverages

Business Owners Policy / Commercial PackageLiability and property components evaluated together

What it is

A Business Owners Policy commonly combines liability and property coverages for eligible businesses. A Commercial Package Policy may combine multiple commercial coverage parts depending on the account and carrier.

Why businesses like yours commonly carry it

Businesses with premises, contents, inventory or other property exposures may ask GIB to evaluate whether liability and property components can be packaged where appropriate.

Possible coverage gap

Eligibility, included coverages and package structure vary by carrier. Commercial Property may also be written separately rather than as part of a package.

Learn more about Business Owners Policy / Commercial Package
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What California business owners say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Who needs industrial insurance in Nevada

Any Nevada employer with employees needs industrial insurance — Nevada's term for workers compensation — required unless a signed exemption affidavit is on file for eligible owners.

The exemption process is specific: it's not automatic just because an owner is also performing the work — the affidavit has to be filed and current.

The actual statutory framework is the Nevada Industrial Insurance Act, NRS Chapters 616A-616D, administered by the Division of Industrial Relations (DIR). The officer/owner exemption mechanism runs through NRS 616B.624 specifically — certain officers and managers may reject coverage, but the rejection has to be made in writing to both the company and the insurer, and can only be rescinded the same way, in writing. An injured employee is a workers comp matter, but an injured visitor, tenant or other subcontractor generally is not; that exposure belongs on general liability coverage in Nevada.

Required unless a signed exemption affidavit is on file
Applies once the business has employees
The exemption isn't automatic — it requires a filed affidavit
Confirm current exemption status rather than assuming it applies

What drives Nevada industrial insurance premium

Payroll by classification is the primary rating basis — accurate classification against actual duties matters as much in Nevada as anywhere else.

Loss experience over time, reflected in the Experience Modification Rate, can move premium meaningfully and is increasingly requested directly by general contractors as prequalification.

Payroll classification accuracy is the primary premium driver
Misclassification tends to surface as additional premium at audit
X-Mod reflects loss experience relative to similar businesses
GCs increasingly request X-Mod directly

Audits and what to expect

Nevada industrial insurance premium is typically estimated up front and trued up against actual payroll at audit — respond to audit requests promptly to avoid a less favorable estimate.

Maintain accurate payroll and classification documentation throughout the policy period, not just when an audit notice arrives.

Premium is trued up against actual payroll at audit
Respond to audit requests promptly
A missed audit can default to a less favorable estimate
Maintain accurate records year-round, not just at audit time

Contract-driven requirements in Nevada

Nevada general contractors, especially on larger commercial and gaming-adjacent projects, commonly require a waiver of subrogation — a specific endorsement, not automatic.

Confirm the exact wording a specific contract requires rather than assuming standard coverage already satisfies it.

Waiver of subrogation often required, especially by larger GCs
It's a specific endorsement, not automatic
Confirm exact wording required by the contract
Larger commercial projects may have specific requirements

A realistic scenario: a misclassified crew

A Nevada contractor running both field crews and office staff commonly lumps everyone into one payroll classification on the application, instead of separating field and clerical work the way the policy is actually priced.

A concrete version of this: a Las Vegas Valley concrete-flatwork crew of 11 plus 1 dispatcher gets reported entirely under the concrete labor code because it's simpler at application. The dispatcher's payroll should be rated under a much lower clerical code — folding it into the concrete code overstates premium every year it goes uncorrected.

Illustrative only — this describes a typical pattern, not an actual case or guaranteed outcome. Combining classification codes usually means overpaying on the clerical portion of payroll and can also complicate a claim if the injured worker's actual duties don't match the code reported. Report payroll by the classification each employee actually works, not one blended code.

Combining classification codes often means overpaying on clerical payroll
A mismatched code can complicate a claim after an injury
Report payroll by actual duties, not one blended code
Confirm the classification with the carrier and rating bureau before binding

Getting industrial insurance coverage in place

Share your NSCB class, current payroll and employee count, and your exemption status if applicable.

Gleason Insurance Brokers places industrial insurance for Nevada contractors — call 844-978-7283 or request a quote to get started.

Share NSCB class, payroll and employee count
Note current exemption status if applicable
We place coverage across CA, AZ, NV, TX and UT
Begin with a quote request, or call 844-978-7283

Exclusions and exposures that matter in Nevada industrial insurance

Extreme summer heat across the Las Vegas Valley drives real, recurring heat-illness claims on outdoor construction work, similar to Arizona's exposure — a documented heat-safety program is a genuine underwriting positive, not a formality.

Nevada's gaming and hospitality-adjacent construction work (Strip-area renovations, resort buildouts) can carry different classification and staffing patterns than residential subdivision work in the same state — describe the actual project type rather than a generic 'Nevada construction' label.

Heat illness is a real, tracked exposure across the Las Vegas Valley's outdoor trades
Gaming/hospitality-adjacent commercial work can carry different classification patterns
Reno-Tahoe's cooler, higher-elevation climate carries less heat exposure than Las Vegas
Describe the actual project type rather than one generic label

Nevada industrial insurance submission checklist

Have the following ready for a Nevada industrial insurance submission:

NSCB license number and class (A, B or C)
Current payroll by classification code, not a single blended figure
Established X-Mod if available, or years in business if not yet established
Three years of loss runs, with a note on any claim that appears
Any Strip-adjacent or gaming/hospitality project flagged separately from residential work

Frequently asked questions

10 questions — start typing to filter

What is industrial insurance in Nevada?

It's Nevada's term for workers compensation — required for employers with employees, unless a signed exemption affidavit is on file for eligible owners.

Is the Nevada owner exemption from industrial insurance automatic?

No — it requires filing a signed exemption affidavit. It isn't automatic just because an owner is also performing the work.

What determines my Nevada industrial insurance premium?

Payroll by classification is the primary driver, along with your Experience Modification Rate once established.

How does an industrial insurance audit work in Nevada?

Premium is typically estimated up front and trued up against actual payroll at audit — respond to audit requests promptly.

Do Nevada general contractors typically require a waiver of subrogation?

Often yes, especially on larger commercial projects — it's a specific, requestable endorsement, not automatic.

Does a new Nevada business have an established X-Mod right away?

Generally not — new businesses need sufficient qualifying payroll and claims experience before an experience modification is established.

Does Gleason Insurance Brokers place industrial insurance in Nevada?

Yes — we place industrial insurance (workers compensation) for Nevada contractors alongside our other licensed states.

Does it matter whether I use an agent or a broker for Nevada workers comp?

It can. An agent generally represents a single carrier's offering, while an independent broker like Gleason Insurance Brokers can bring your Nevada workers comp submission to several markets at once. For a contractor with a specific classification mix or claims history, having more than one carrier looking at the account tends to produce better options.

Do Nevada industrial insurance carriers expect a documented safety program?

Yes, and note the Nevada vocabulary: the coverage is industrial insurance, administered by the Division of Industrial Relations under the Nevada Industrial Insurance Act. Carriers generally expect a written program matched to the trade's real hazards with documented incident and near-miss reporting. Two specifics carry weight here: a documented heat-safety program for outdoor work across the Las Vegas Valley is a genuine underwriting positive, and gaming- and hospitality-adjacent buildout work has staffing and classification patterns that differ from residential subdivision work, so a program written for the actual project type reads better than a generic one.

Does gaming or hospitality-adjacent construction work affect Nevada industrial insurance classification?

It can — Strip-area renovation and resort buildout work sometimes carries different classification and staffing patterns than residential subdivision work. Describe the actual project type on your submission rather than a single generic Nevada construction label.

Additional official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Updated October 12, 2026