Gleason Insurance Brokers

General Liability · Workers' Comp · Commercial Auto · Pollution Insurance · Surety Bonds Start a Business Insurance Quote Today

A newly built retail center with stone and brick storefronts and a fresh parking lot, the far end still under construction with staged materials and a lift — commercial contractors general liability

California commercial insurance

Commercial Contractor Insurance California

844-97-USAVE

Commercial contractor risk scales with the project — higher total insured values, owner and lender insurance specifications layered on top of standard coverage, and often a wrap-up program governing the whole jobsite rather than each contractor's own policy alone.

  • General Liability & Builders Risk
  • Umbrella Limits
  • Additional Insured Wording

Reviewed by David Gleason, Principal — October 12, 2026

Next Level Experience. Insurance Done Right.

CaliforniaGeneral information only, not legal advice — illustrative scenarios and coverage, subject to change without notice. Content may be out of date or contain errors, and requirements vary by city, county, state, agency, project, contract, carrier and policy, among other factors; verifying what applies to your own situation is your responsibility. Full disclaimer

Interactive coverage guide

Build a coverage stack around how the business actually operates.

Start with the preselected industry or trade, then adjust the operational questions. The commonly considered stack updates live. Keep the coverages you want GIB to evaluate, remove ones you do not want included in your quote request, and add other available lines before continuing.

Common Starting Coverages

General LiabilityThird-party injury and property damage

What it is

General Liability commonly addresses covered third-party bodily injury, property damage and certain personal or advertising injury claims, subject to the policy.

Why businesses like yours commonly carry it

Businesses commonly use it as a starting liability policy and to satisfy customer, landlord or contract requirements.

Possible coverage gap

General Liability is not intended to replace policies for employee injuries, business vehicles, owned property, cyber events or professional errors.

Learn more about General Liability

Commonly Added Based on Operations

Contractor Equipment / Inland MarineMobile tools, equipment and property away from premises

What it is

Inland Marine is commonly used for tools, equipment and certain mobile property that moves between locations or jobsites.

Why businesses like yours commonly carry it

Contractors frequently move tools, testing equipment and mobile machinery among jobsites.

Possible coverage gap

General Liability should not be assumed to insure the business's own tools and equipment against theft or physical damage.

Learn more about Contractor Equipment / Inland Marine
Cyber Liability & Data BreachCyber events, data and system interruption

What it is

Cyber insurance may address certain first-party and third-party losses from covered data breaches, cyberattacks, ransomware and system interruption, depending on the policy.

Why businesses like yours commonly carry it

Contractors commonly use email, electronic banking, project platforms, payroll systems and cloud document storage.

Possible coverage gap

General Liability generally should not be assumed to address data breach response, ransomware or network interruption.

Learn more about cyber insurance for contractors

Exposure-Dependent Coverages

Installation FloaterMaterials awaiting or undergoing installation

What it is

An Installation Floater may cover certain materials and equipment in transit, temporary storage and during installation, subject to the policy.

Why businesses like yours commonly carry it

Businesses responsible for materials before final installation commonly consider this coverage.

Possible coverage gap

A basic liability policy generally should not be assumed to cover the insured's materials against physical loss before installation is complete.

Learn more about Installation Floater
Builder's RiskProject property during construction

What it is

Builder's Risk may insure covered buildings, materials and certain project property while construction is underway.

Why businesses like yours commonly carry it

Owners, developers and contractors commonly consider it when a structure or major renovation is exposed during construction.

Possible coverage gap

Commercial Property and General Liability are not automatic substitutes for course-of-construction property coverage.

Learn more about Builder's Risk
Contractors Pollution LiabilityPollution conditions and cleanup liability

What it is

Pollution Liability may address covered cleanup costs and third-party injury or property damage arising from pollution conditions.

Why businesses like yours commonly carry it

Businesses working with fuels, chemicals, soil, water, demolition or environmental conditions may have pollution exposures.

Possible coverage gap

Standard General Liability commonly contains pollution exclusions or limitations.

Learn more about Contractors Pollution Liability
Umbrella / Excess LiabilityAdditional limits above scheduled liability policies

What it is

Umbrella or Excess Liability may provide additional limits above identified underlying liability policies, subject to its own terms and exclusions.

Why businesses like yours commonly carry it

Businesses with larger contracts, vehicles, public exposure or higher severity potential commonly consider additional limits.

Possible coverage gap

An umbrella does not automatically broaden every exclusion or sit over every policy unless the issued terms say it does.

Learn more about Umbrella / Excess Liability

Loading quote and requirements options…

Educational guidance only. Results are not a coverage recommendation, quote, binder, policy interpretation, or guarantee of coverage. Actual needs, availability, forms, limits, exclusions and requirements vary. A licensed insurance professional should review the complete risk and issued policy terms.

Verified Google reviews

What contractors say about us

5.0 / 5from 7 Google reviews

Reviews reflect individual client experiences and are not a guarantee of coverage, pricing or results.

91 Enterprise LLC

91 Enterprise LLC

March 24, 2026

We are using Gleason insurance for our commercial auto policy and GL policy. David is the best insurance broker I've worked with — very honest, responsive, and knowledgeable. Highly recommend.

Fito Plumbers

Fito Plumbers

February 20, 2026

We have been working with David at Gleason Insurance Brokers for 8+ years. David always goes above and beyond to make sure we have the appropriate coverages. He explains everything in detail and makes sure we feel confident and understand all of our policies. He is always available and responds right away!

Barry Stay

Barry Stay

February 17, 2026

David provides great service and I highly recommend him for your insurance needs.

Why commercial risk scales differently than residential

Commercial work — office, retail, industrial and mixed-use — typically carries a higher total insured value per project than residential work, which pushes general liability, builders risk and umbrella limits higher to match.

Read more

A limit structure sized for a handful of single-family homes doesn't automatically scale to one mid-size commercial building.

Commercial owners, developers and lenders also tend to have their own formal insurance specifications — specific additional insured wording, primary and noncontributory language, waiver of subrogation, and sometimes a minimum AM Best carrier rating — that need to be confirmed against the actual policy before bidding, not discovered after award. This is especially true for life-safety and specialty trades common on commercial projects: fire sprinkler, HVAC and mechanical, electrical and solar, fiber optic and low voltage, and welding subs often carry code-driven requirements beyond standard GL.

Higher total insured values push GL, builders risk and umbrella limits higher than typical residential work
Commercial owners and lenders often specify exact AI wording and minimum carrier ratings
Read the actual insurance specification in the contract documents before bidding
A limit structure sized for residential work doesn't automatically fit commercial-scale projects

Trades we commonly place on commercial projects

Commercial build-outs and ground-up commercial construction draw on a broader trade roster than residential work, often with code-driven or life-safety requirements layered on top.

Read more

We place coverage for HVAC, mechanical and refrigeration, commercial electrical, fire sprinkler and fire protection, communications and low voltage, and welding work on commercial jobs statewide.

The structural and site side of a commercial project brings its own specialty trades — sheet metal fabrication, structural metal fabrication, commercial framing, demolition, excavation and site prep, and concrete and paving for the lot itself. Plumbing rounds out the core mechanical, electrical and plumbing (MEP) trades on most commercial jobs.

Code-driven trades: fire sprinkler, HVAC, electrical, communications
Structural and fabrication: sheet metal, structural metal, welding
Site and shell: excavation, concrete and paving, framing, demolition
Every trade page below links back here and to the other project-type hubs

The core coverage lines a commercial program actually needs

Commercial contractor programs start with the same general liability, workers compensation and commercial auto baseline as any contractor, but limits and endorsements typically scale up with project size and owner/lender requirements.

Read more

Contractor equipment and inland marine coverage matters more here given the equipment values on a commercial job.

Larger commercial jobs bring specific requirements most residential work never triggers — OCIP/CCIP wrap-up enrollment on owner-controlled programs, real umbrella and excess liability limits, and often professional liability/E&O if design-assist or design-build work is involved.

General liability, workers comp and commercial auto, scaled to project size
Contractor equipment and inland marine for commercial-scale equipment values
OCIP/CCIP wrap-up enrollment on owner-controlled programs
Umbrella/excess liability and professional liability/E&O for larger scope

Tenant improvement work: a distinct exposure

Tenant improvement (TI) work — build-outs inside an occupied or soon-to-open commercial building — carries liability exposure that ground-up commercial construction doesn't: other tenants, building common areas, and the property owner's own operations are all active around your crew, not sitting on vacant land.

Read more

TI contracts also frequently require the contractor to carry coverage that names the building owner and property manager as additional insureds on an ongoing basis, not just for the duration of the specific build-out — confirm how long that AI obligation actually runs before assuming it ends at project completion. See our dedicated Remodel & Tenant Improvements Contractor Insurance page for the existing-condition and occupied-space exposure TI work shares with residential remodel work.

TI work happens around active tenants and building operations, not on vacant land
Confirm how long an additional insured obligation runs — it may extend past project completion
Property manager and building owner AI requirements are common on TI contracts
Existing-condition documentation before starting TI work reduces dispute risk

How risk transfer works through a property manager

Building Owner → Property Manager → Contractor or Vendor

A property manager hires on the owner’s behalf, which is why the insurance requirement usually names two companies rather than one. Open a handoff to see what commonly travels with it.

Building Owner — the entity that holds title
  • The management agreementSets what the manager may do in the owner’s name, including hiring contractors and setting the insurance they have to carry. It is the reason a requirement can arrive from a company that does not own the building.
  • The manager named on the owner’s policiesManagers commonly ask to be added to the owner’s liability cover for the management of the premises. It is why the manager has an insurable interest in the building at all, and why it appears on paperwork alongside the owner rather than instead of them.
  • The manager’s own professional liabilitySeparate from anything the building carries. Real estate errors and omissions responds to the management service itself — leasing decisions, habitability complaints, handling of deposits — none of which a contractor’s policy touches.
  • Certificate, plus the endorsements behind itA certificate evidences that a policy existed on the day it was issued. It is not proof that any particular endorsement sits on that policy, which is why a requirement is commonly checked against the endorsement itself.

Worth reading as background rather than as anything a contractor has to satisfy. It is the part that explains the two names on the requirement further down.

Property Manager — acting as agent for the owner
Contractor or Vendor — the business doing the work

The limits a contract asks for, and what each one means

Management companies commonly set required limits across a whole portfolio rather than per building, so the figure a contractor is handed may reflect the largest property on the roster rather than the one being worked on. One million dollars per occurrence with a two million dollar general aggregate is a combination many management agreements use, but the numbers vary by portfolio, by building and by the kind of work.

Per occurrence
The most the policy generally pays for any one covered occurrence.
General aggregate, sometimes per location
A contractor servicing several buildings for the same manager may find one shared aggregate spread across all of them. Applying it per project or per location is its own endorsement.
Products and completed operations aggregate
The bucket claims fall into after the work is finished, which is where completed-operations additional insured status becomes the relevant one.
Umbrella or excess above it
Commonly asked for on larger portfolios. If the underlying limits do not match what the umbrella requires beneath it, the tower may not respond as the agreement assumes.

OCIP/CCIP exposure on larger commercial jobs

Larger commercial projects increasingly run under an Owner or Contractor Controlled Insurance Program (OCIP/CCIP) — a wrap-up program where the project sponsor provides GL and workers comp coverage for all enrolled contractors on that specific job, replacing each contractor's own policy for that project only.

Read more

Working under a wrap-up doesn't eliminate the need for your own standing coverage — off-project work, excluded coverage lines, and the period before/after enrollment still need your own policy in force. See our OCIP/CCIP Wrap-Up Programs page for how enrollment actually works.

OCIP/CCIP wrap-ups provide project-specific GL and workers comp for enrolled contractors
Your own standing coverage is still needed for off-project work and excluded lines
Confirm enrollment dates — coverage gaps can exist before/after the wrap-up period
Wrap-up enrollment doesn't replace your umbrella/excess needs on non-enrolled work

Higher limits: umbrella and excess for commercial-scale work

Commercial contracts more often specify umbrella/excess limits well above what a residential-focused GC typically carries — $5 million or $10 million umbrella requirements aren't unusual on mid-size commercial projects, layered on top of underlying GL, auto and employers liability limits that also need to support that structure.

Read more

Confirm your underlying limits actually support the umbrella you're quoting — an umbrella policy follows the form of what's underneath it, and a mismatch between the two is a gap that isn't obvious until a large claim tests it.

$5M-$10M umbrella requirements are common on mid-size commercial contracts
Underlying GL, auto and employers liability limits must support the umbrella structure
An umbrella follows the form of its underlying policies — confirm they're consistent
See the Umbrella & Excess Liability page for how limits stack

What tends to raise the bar

Where higher limits and extra endorsements are commonly requested

Patterns this agency typically sees, not a statement of what any particular project, agency or carrier will ask for.

Projects around two million dollars and up

Mid-sized and larger jobs are where umbrella or excess limits start being written into the insurance exhibit, and where a per-project aggregate is most often asked for. The figure is a rough threshold we tend to see rather than a rule — plenty of smaller contracts ask for more, and some larger ones ask for less.

Pulling a permit with a city or county

Some jurisdictions set their own insurance conditions before a permit is issued, separate from anything the project owner asks for. It is worth reading the permit conditions as its own document rather than assuming the contract covers it.

Encroachment permits and work in the public right of way

Working in a city, county or Caltrans right of way commonly carries its own limits, its own additional insured wording naming the agency, and sometimes a bond as well.

Public works

The awarding agency writes its requirements into the bid package, and they are rarely identical to what a standard commercial policy already provides. Bonding, DIR registration and certified payroll usually travel with them.

Property management companies and landlords

The manager, the building owner and sometimes a lender are commonly all named, and the waiver of subrogation is often mutual. A management company typically has one standard insurance exhibit it applies to every vendor.

Commercial retail, shopping centers and malls

Mall and shopping center rules commonly set named additional insureds and specific limits before anyone is cleared to work on site, and the requirement frequently comes from the center itself or its property management company rather than from the tenant who hired you.

High-rise buildings

Height, occupancy and water damage exposure commonly push limits up and bring specific endorsements with them. Building rules for contractor access are frequently a separate document again.

Colleges, universities and school districts

Institutional contract templates commonly specify limits and endorsements directly, and depending on the work may ask about coverages a construction policy does not carry as standard.

Caltrans and other government work

State and federal agencies commonly specify their own forms, their own wording and their own limits, and are usually the least flexible about substitutions.

What tends to be asked for alongside the higher limits

Per-project aggregateCG 25 03 or CG 25 04
The one that surprises people most. A general aggregate is normally shared across every job running in the policy term, so a claim on one project can erode the limit the next contract assumed was there. A per-project aggregate sets a limit for the designated project instead.
Additional insured, scheduled or blanketCG 20 10 and CG 20 37
Ongoing operations and completed operations are two separate endorsements, and larger contracts commonly ask for both.
Primary and non-contributoryoften CG 20 01
Decides whether the downstream policy responds first or shares with the upstream party’s own cover.
Waiver of subrogationCG 24 04
Frequently named alongside additional insured status rather than instead of it.
Higher umbrella or excess limits
Commonly the first thing an insurance exhibit raises. If the underlying limits do not match what the umbrella sits above, the tower may not respond the way the contract assumes.

Two real examples, published by the agencies themselves

Reading an actual insurance clause is worth more than any summary of one. Both of these are public, and they ask for different things — which is the point.

  • City of Los Angeles Bureau of Engineering — liability insurance for permitsStates a commercial minimum of $1 million with a $2 million aggregate, a thirty-day written cancellation notice, and the City named both as certificate holder AND as additional insured. It also expects proof to stay on file for as long as the encroachment exists, not just through construction.
  • Caltrans Encroachment Permits Manual — Chapter 200, section 203.3Asks for an endorsement naming the State of California, the Department and its directors, officers, employees and agents as additional named insureds — and for the certificate AND the endorsement to be furnished. A good illustration of why a certificate on its own is rarely what an agency means.

New commercial construction vs. commercial renovation/TI

Ground-up commercial construction concentrates risk in builders risk sized to full project value and completed operations on a never-occupied structure, while commercial renovation and TI work adds occupied-building liability and existing-condition exposure on top of standard coverage — two different risk profiles that shouldn't be priced identically.

Read more

If your commercial operations span both new construction and renovation/TI work, see our New Construction Contractor Insurance page for how ground-up work is classified and covered differently.

Ground-up commercial construction concentrates risk in builders risk and completed operations
Renovation and TI work adds occupied-building liability on top of standard coverage
These two profiles shouldn't be priced or classified identically
New construction is covered in depth on its own dedicated page
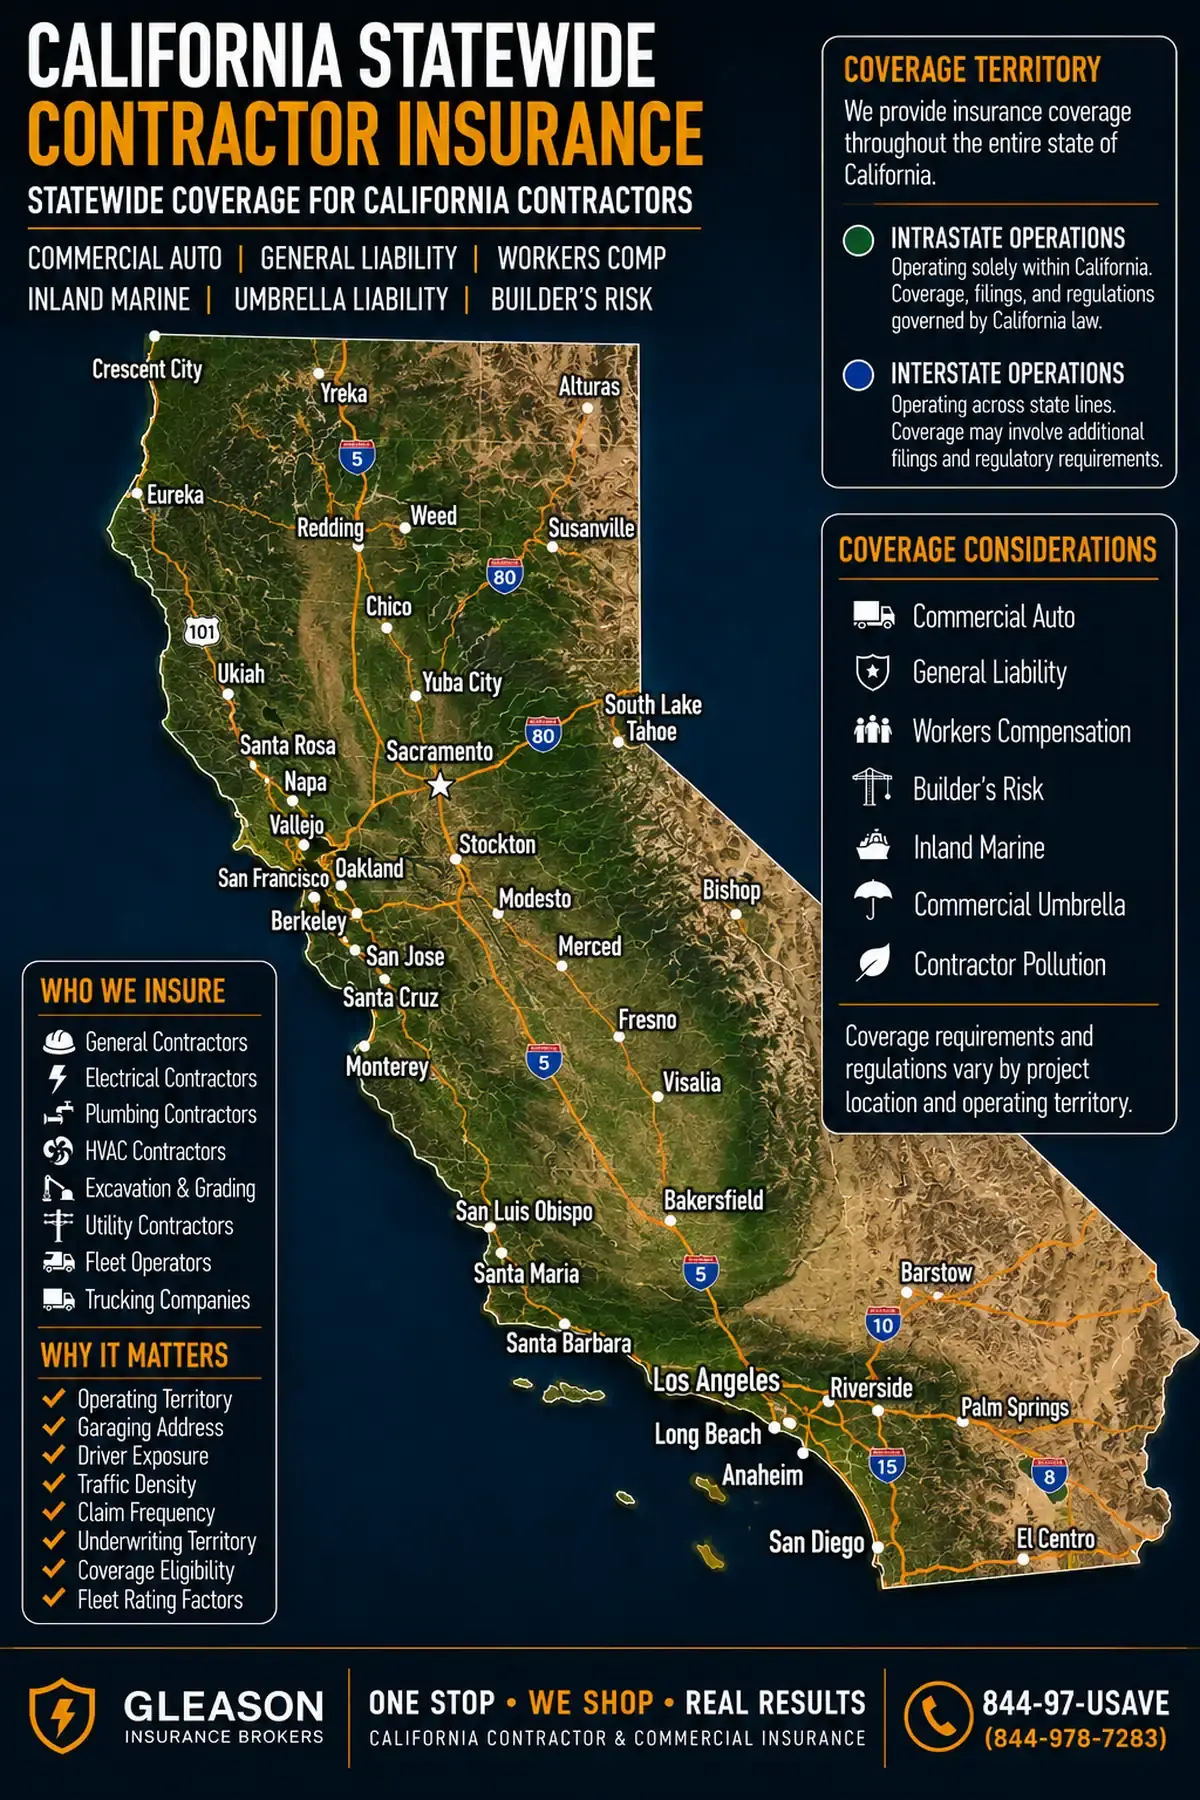
California statewide contractor insurance coverage map showing intrastate and interstate operations from Sacramento to San Diego — Gleason Insurance Brokers

One Stop · We Shop · Real Results

844-978-7283
  • General contractors
  • Electrical contractors
  • Plumbing contractors
  • HVAC contractors
  • Excavation and grading
  • Utility contractors
  • Fleet operators
  • Trucking companies
  • Operating territory
  • Garaging address
  • Driver exposure
  • Traffic density
  • Claim frequency
  • Underwriting territory
  • Coverage eligibility
  • Fleet rating factors
  • Commercial auto
  • General liability
  • Workers compensation
  • Builders risk
  • Inland marine
  • Commercial umbrella
  • Contractor pollution

Radius, territory, vehicle use, jobsite locations and garaging ZIP code can all influence commercial insurance pricing and underwriting eligibility. The zones shown describe how far this agency places coverage; they are not a statement of what any policy covers.

A realistic scenario: a wrap-up enrollment gap

A commercial subcontractor enrolls under a project's CCIP for GL and workers comp, but continues bidding and performing smaller non-enrolled jobs during the same period — if their own standing policy lapses because they assume the wrap-up covers everything, that non-enrolled work has no GL coverage at all.

Read more

This is offered as a general, illustrative example of how this type of situation commonly plays out — not a specific case, and not a promise of how any real claim would be decided. For an actual situation, the specific policy and program language and a licensed attorney are the right resources, not this page.

Wrap-up enrollment covers only the specific enrolled project, not a contractor's other work
Letting a standing policy lapse during wrap-up enrollment is a common, serious mistake
Confirm exactly what is and isn't covered under the wrap-up before relying on it
This scenario is illustrative only, not a specific claim outcome or legal guidance

From our case files: one water loss, a new insurance market

Commercial interiors work puts a contractor above, beside or below someone else's business.

Read more

In one of our files, a pipe burst while a general contractor was working on an upper floor, soaking the suite below and damaging the tenant's electronics and medical equipment. General liability paid the tenant's claim, but the carrier would not renew, and the next carrier's premium was about 90% higher (case study 5).

Building your commercial program with Gleason Insurance Brokers

We build commercial contractor programs around your actual project scale, owner/lender specifications, and wrap-up exposure — not a generic package that treats a small TI job the same as a ground-up commercial building.

Read more

Share your current operations, typical project size and any owner/lender insurance specifications you've been given, and we'll identify what's already well-structured and what needs attention. Call 844-978-7283 or request a quote to start.

Commercial and tenant improvement coverage isn't limited to California either — see Arizona, Nevada, Texas and Utah for multi-state commercial contractors.

For larger commercial work specifically, see our public works survival guide and construction insurance lines overview for the detail a commercial submission typically needs.

Programs built around your actual project scale and TI vs. ground-up mix
Owner, lender and OCIP/CCIP requirements reviewed against your real contracts
Umbrella and excess limits structured to actually match your underlying coverage
Request a quote online, or call 844-978-7283

Where commercial development is concentrated

Office, retail, hospitality and mixed-use commercial construction in California is concentrated in the state's largest metro cores, where redevelopment and institutional work continue even when new supply slows.

Read more

The markets below are where that activity is real rather than announced.

Warehouse, distribution and logistics projects follow a different map entirely — they cluster in the Inland Empire and the northern San Joaquin Valley rather than in the metro cores — and they carry exposures a commercial office build does not, from tilt-up panel bracing to high-pile storage fire protection. Those are covered on their own page: industrial and warehouse contractor insurance.

Where a commercial contractor works changes the insurance conversation less than what it builds does, but it changes the contract requirements a good deal — municipal and institutional owners in these markets tend to run their own insurance specifications, and those arrive as a document to be read rather than a standard to be assumed.

Los Angeles — major mixed-use development continuing downtown and across the metro Los Angeles contractor coverage
San Diego — continued office, life-science and mixed-use commercial activity insurance for San Diego contractors
San Jose — ongoing office and mixed-use development tied to Silicon Valley demand San Jose coverage
Oakland / San Francisco — continued institutional and mixed-use commercial redevelopment Oakland/SF coverage
Sacramento — steady commercial activity tied to the region's broader growth Sacramento area contractor insurance
Irvine — one of Orange County's most active business-park submarkets coverage in Irvine
Santa Ana — adaptive-reuse conversions alongside new commercial projects Santa Ana contractor insurance
Santa Clara — continued Silicon Valley office construction insurance for Santa Clara contractors

Frequently asked questions

11 questions — start typing to filter

Is commercial contractor insurance different from residential?

Yes — commercial work typically requires higher limits, more formal owner/lender insurance specifications, and more frequent OCIP/CCIP wrap-up coordination than residential-scale work.

What is an OCIP or CCIP?

An Owner or Contractor Controlled Insurance Program — a wrap-up program where the project sponsor provides GL and workers comp for all enrolled contractors on that specific project only.

Does OCIP/CCIP enrollment replace my own insurance?

Only for that specific enrolled project. Your own standing policy is still needed for off-project work, excluded coverage lines, and periods outside the enrollment dates.

What limits do commercial contracts typically require?

$5M-$10M umbrella/excess requirements are common on mid-size commercial projects, layered on underlying GL, auto and employers liability limits sized to support that structure.

What's different about tenant improvement (TI) work?

TI work happens inside occupied or soon-to-open buildings around other tenants and the property owner's operations, and often carries an additional insured obligation that runs longer than the specific build-out.

How is new commercial construction different from commercial renovation?

New ground-up construction concentrates risk in builders risk and completed operations on a never-occupied structure; renovation and TI work adds occupied-building liability on top of standard coverage.

Do I need a minimum AM Best carrier rating for commercial contracts?

Many commercial owners and lenders specify one — confirm the actual contract language before bidding, since it varies by project and isn't a universal requirement.

Can Gleason help if I do both residential and commercial work?

Yes — see our dedicated Residential Contractor Insurance page, and we can coordinate both programs together under one broker relationship.

Do fire sprinkler, HVAC or electrical subs need higher limits on commercial jobs?

Often yes — life-safety and code-driven trades like fire sprinkler, HVAC/mechanical and electrical work commonly carry higher owner-required limits on commercial projects than the same trade would on residential work. Confirm the specific contract requirement rather than assuming a standard limit applies.

What's the difference between ground-up commercial construction and tenant improvement insurance needs?

Ground-up commercial construction concentrates risk in builders risk and completed operations on a never-occupied structure; tenant improvement work adds occupied-building liability and additional-insured obligations to the property owner and manager that can run longer than the build-out itself.

What is commercial construction insurance?

Commercial construction insurance is coverage built around commercial-scale project work — larger limits, umbrella capacity, and often OCIP/CCIP wrap-up coordination — as opposed to a program sized for smaller residential jobs. See the sections above for what actually changes at commercial scale.

Areas we serve near Commercial Contractor Insurance California

Coverage placed for contractors and businesses operating in Commercial Contractor Insurance California and these surrounding communities.

View ZIP codes we serve (46)

Los Angeles, CA: 90001, 90002, 90003, 90004

San Diego, CA: 92101, 92102, 92103, 92104

San Jose, CA: 95025, 95101, 95103, 95106

Oakland, CA: 94601, 94602, 94603, 94604

Sacramento, CA: 94203, 94204, 94205, 94206

Irvine, CA: 92602, 92603, 92604, 92606

Ontario, CA: 91758, 91761, 91762, 91764

Fontana, CA: 92331, 92334, 92335, 92336, 92337

Fremont, CA: 94536, 94537, 94538, 94539, 94555

Stockton, CA: 95201, 95202, 95203, 95204

Riverside, CA: 92501, 92502, 92503, 92504

Official resources

Verify current licensing, regulatory and program requirements directly with the responsible agency — this is general information, not legal advice, requirements change without notice, and what is summarized here may be out of date or contain errors. Confirming what applies to your own city, project, contract and policy is your responsibility.

Explore Related Coverage and Contractor Resources

Related coverage
Guides, trades and resources

Updated October 12, 2026